Wendy Schmidt · 22 October 2026
Monetary Trend Updates and Their Role in Reshaping Eastern Perimeter Resource Distributions for Digital Service Providers
Monetary policy adjustments across major economies have continued to influence how digital service providers allocate resources along the eastern edges of the European Union. Central bank decisions on interest rates and currency stability directly affect operational costs for companies managing data centers, cloud networks, and content delivery systems in countries such as Poland, Romania, and the Baltic states. Figures released in October 2026 by the European Central Bank show a measured reduction in key lending rates, which has prompted several providers to reassess capital expenditure plans in these perimeter markets.
Policy Shifts and Currency Movements
Exchange rate fluctuations between the euro and regional currencies have created new cost structures for digital firms that rely on imported hardware and international bandwidth contracts. Data compiled by the European Central Bank indicates that the euro strengthened modestly against the Polish zloty and Romanian leu during the third quarter of 2026, altering the economics of server procurement and maintenance contracts. Providers have responded by adjusting procurement timelines and renegotiating long-term agreements with regional suppliers to lock in favorable terms before further volatility occurs.
Researchers tracking these movements note that similar patterns emerged after earlier rate cycles in 2023 and 2024, when providers accelerated investments in lower-cost eastern locations while hedging against currency swings. The current environment adds layers of complexity because inflation differentials between core eurozone economies and eastern perimeter states remain uneven, according to the same European Central Bank dataset.
Resource Allocation Patterns
Digital service companies have begun redirecting portions of their infrastructure budgets toward eastern perimeter facilities where energy prices and labor costs remain comparatively stable. Reports from the International Monetary Fund highlight that sustained lower borrowing costs in several member states have encouraged expansion of edge computing nodes and regional content caches. These adjustments allow providers to reduce latency for local users while managing exposure to broader monetary tightening elsewhere.
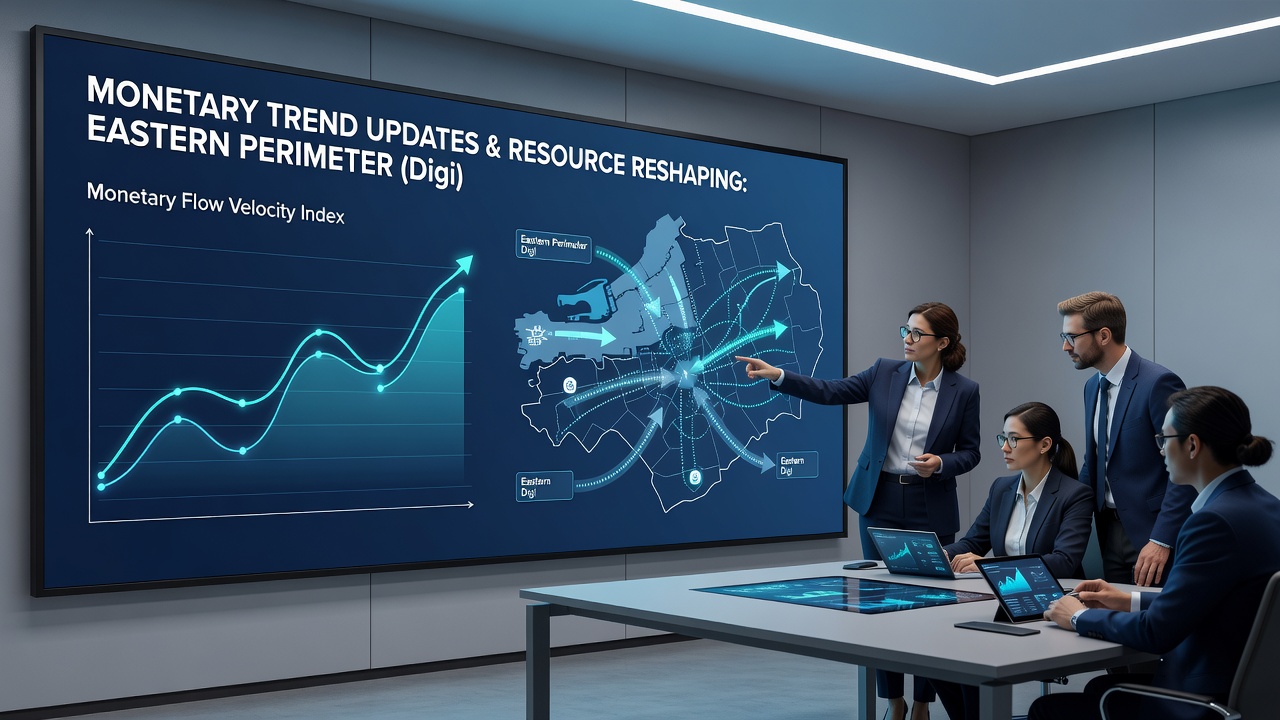
One study released by an academic consortium in October 2026 examined capital flows into data infrastructure across eight eastern member states and found measurable increases in committed projects following the latest rate announcements. The analysis linked these commitments to improved access to euro-denominated financing, which has lowered the effective cost of multi-year equipment leases and fiber network upgrades. Providers have also shifted personnel resources, moving technical support teams and network operations centers to cities where real estate and utility expenses align more closely with revised budget projections.
Impact on Service Delivery Models
Monetary updates have further influenced how providers structure subscription pricing and service-level agreements for customers in the region. When borrowing costs decline, companies gain flexibility to extend credit terms or bundle additional storage and processing capacity without immediate price increases. Observers note that several major platforms updated their eastern European offerings in late 2026 to reflect these revised cost bases, expanding available capacity in markets previously constrained by higher financing expenses.
Regional trade data shows corresponding growth in cross-border data traffic volumes between perimeter states and core European hubs, driven partly by the redistribution of processing workloads. Providers have cited improved predictability in funding markets as a factor enabling these expansions, though they continue to monitor secondary effects such as potential rebound inflation or renewed rate volatility.
Future Considerations
Analysts examining October 2026 policy statements emphasize that ongoing coordination between national central banks and the European Central Bank will remain central to investment planning for digital infrastructure. Continued tracking of monetary aggregates and regional inflation metrics will help determine whether the current redistribution of resources stabilizes or accelerates in coming quarters. Providers have indicated they will maintain flexible deployment schedules to respond to any subsequent adjustments in lending conditions or currency alignments.
Conclusion
Monetary trend updates continue to shape how digital service providers organize and fund their operations along the eastern perimeter of the European Union. Currency movements, interest rate changes, and related financing conditions directly affect decisions on data center placement, network capacity, and personnel distribution. Available data through October 2026 documents measurable shifts in investment patterns and service models, with providers adapting procurement and expansion strategies to align with evolving cost structures. These adjustments reflect broader economic linkages between central bank policies and the operational requirements of digital infrastructure across the region.